
PPF vs SSY 21-Year Return Comparison: Which Scheme Wins
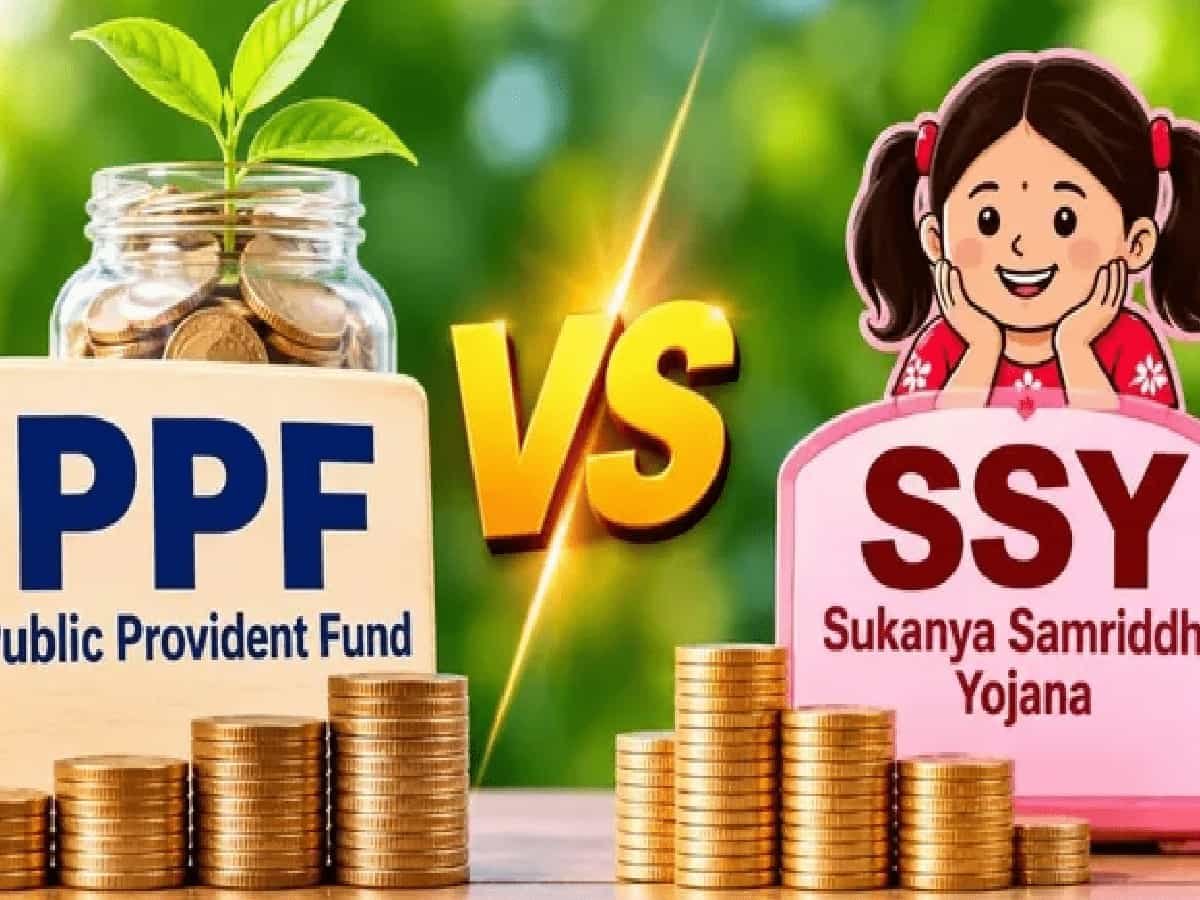
When it comes to long-term wealth creation in India, millions of risk-averse investors continue to prioritize sovereign-backed security over volatile equity markets. Among government-backed small savings instruments, the Public Provident Fund (PPF) and the Sukanya Samriddhi Yojana (SSY) stand out as premier choices for capital protection, tax efficiency, and guaranteed returns.
While both schemes operate under government backing and offer attractive tax benefits under Section 80C, they differ significantly in their target beneficiaries, annual investment caps, compounding mechanics, and prevailing interest rates. As savers navigate financial planning, a frequent question arises: With SSY offering a higher nominal interest rate, does it automatically translate into a larger maturity corpus over a 21-year horizon compared to PPF? A detailed mathematical breakdown reveals how these two pillars of Indian household savings perform side-by-side.
Understanding the Core Differences: Eligibility, Tenure, and Interest Rates
Before diving into long-term compounding calculations, it is essential to examine the structural parameters governing both accounts:
Sukanya Samriddhi Yojana (SSY): Launched as part of the Beti Bachao Beti Padhao initiative, SSY is exclusively designed for the financial security and higher education of a girl child. An account can be opened by a parent or legal guardian for a girl child below the age of 10. The investment tenure for SSY spans 21 years from the date of opening, though mandatory deposits are only required for the first 15 years. For the current quarter ending December 2026, SSY offers an attractive annual interest rate of 8.2%, compounded annually.
Public Provident Fund (PPF): In contrast, PPF is a universal long-term savings vehicle open to any resident Indian citizen. The standard maturity period for a PPF account is 15 years, which can subsequently be extended in blocks of 5 years indefinitely. For a fair comparison over a 21-year timeframe, financial models often extend PPF contributions across the full 21 years. The prevailing PPF interest rate stands at 7.1% per annum, compounded annually.
With SSY enjoying a notable 1.1% interest rate advantage over PPF (8.2% versus 7.1%), many investors assume SSY will invariably generate a much larger absolute corpus. However, compounding outcomes are heavily influenced by annual contribution caps and deposit rules.
21-Year Financial Calculation: Public Provident Fund (PPF)
The Public Provident Fund allows individuals to deposit a minimum of ₹500 and up to a maximum of ₹1.5 lakh per financial year.
Assuming an investor consistently deposits the maximum allowable limit of ₹1.5 lakh every year into a PPF account and extends the tenure to align with a 21-year investment horizon, the compounding trajectory shapes up as follows:
Annual Investment: ₹1,50,000
Total Investment Duration: 21 Years
Total Principal Invested: ₹31,50,000
Assumed Interest Rate: 7.1% per annum (compounded annually)
Estimated Maturity Fund After 21 Years: ₹72.92 Lakh
Total Accumulated Interest Earned: ₹41.42 Lakh
Despite the relatively modest 7.1% interest rate, the sheer power of long-term compounding over 21 years allows the total corpus to more than double the invested principal, generating over ₹41.4 lakh purely in tax-free interest.
Comparative Analysis and Strategic Takeaways for Investors
While a direct mathematical projection shows PPF yielding approximately ₹72.92 lakh under maximum contributions over 21 years, evaluating SSY requires factoring in its unique 15-year deposit rule where compounding continues actively for an additional 6 years without fresh inflows.
Interest Rate Edge: SSY clearly leads on yield, offering 8.2% compared to PPF's 7.1%. For investors seeking maximum returns backed by sovereign safety, SSY provides superior capital growth per rupee invested.
Eligibility & Flexibility: PPF is open to all individuals and offers versatile partial withdrawal and loan facilities after specific operational years. SSY is strictly restricted to families with a girl child and carries lock-in rules tied primarily to the child's education and marriage milestones.
Tax Status: Both schemes enjoy the coveted Exempt-Exempt-Exempt (EEE) tax status in India, meaning contributions, annual interest earned, and maturity proceeds are entirely free from income tax.
Choosing between PPF and SSY ultimately depends on individual life stages and family demographics. For parents planning specifically for a daughter’s future, maximizing the SSY quota remains an unbeatable option due to its superior 8.2% interest rate. For broader individual retirement or long-term wealth planning, PPF remains an indispensable cornerstone of a disciplined financial portfolio.